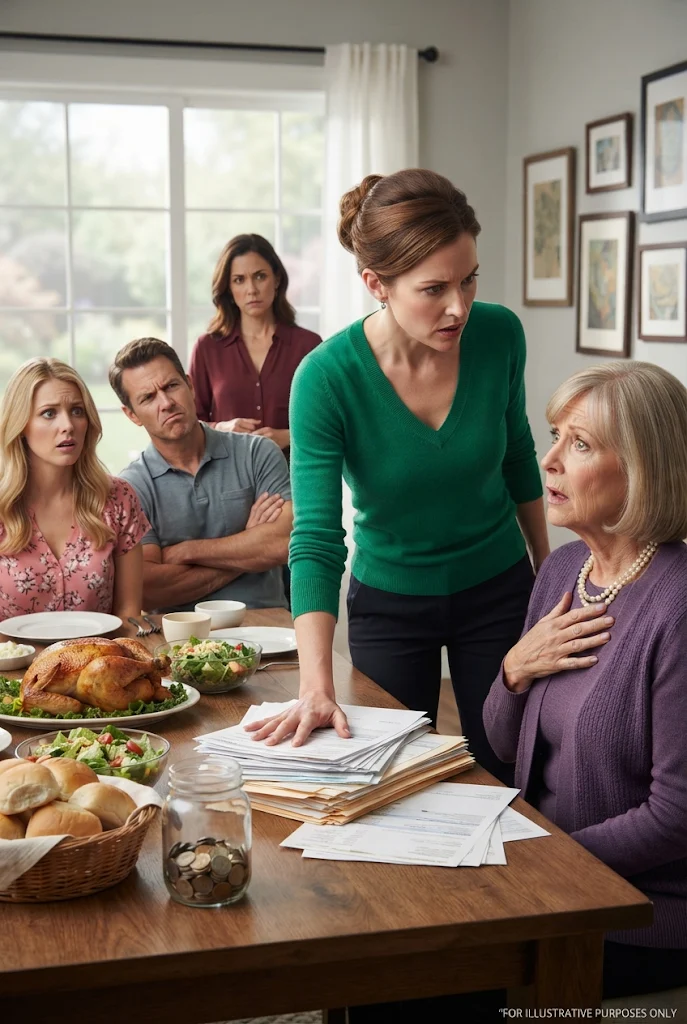
My Daughter Worked Hard to Save $5,400 for Her First College Semester. My Mother Took It to Renovate My Brother’s House, Saying, “She can earn it back.”
My daughter had put aside $5,400 for her first college semester. My mother took it, claiming my brother needed a kitchen renovation. “She can earn it back.” I quietly canceled the $27,000 family resort vacation I’d financed. The next morning, Mom was on the phone from the resort’s reception desk, demanding an explanation.
My daughter’s entire $5,400 college fund had vanished into a supposed remodeling project at my brother’s house. After hearing my mother’s excuse, “She can earn it back.” I canceled our $27,000 family getaway without an argument. By morning, her furious call came from the resort lobby.
The reservation confirmation remained displayed on my phone when Audrey entered our kitchen and spoke six words that changed everything.
“Mom, my savings account is empty.”
I had coffee in one hand and my phone in the other, checking the schedule for a vacation I’d spent four months arranging. Seven nights in four all-inclusive, oceanfront rooms had cost me $27,000.
I’d booked it for all of us because paying was the part of family life that always seemed to fall to me. It never occurred to anyone else to take over.
I’m Brooke Novak, thirty-five, and senior human resources director at a 300-person manufacturing firm. For fifteen years I’ve dealt with compensation, employee benefits, workplace disputes, internal inquiries, and discrepancies buried in financial paperwork. I’ve questioned people whose dishonesty was obvious before they answered.
That professional habit doesn’t disappear when work ends. It was there with me in the kitchen that morning. So was the lifelong financial responsibility my family had silently assigned me: whatever everyone else couldn’t cover, Brooke paid.
Mom, Martha, was sixty-two. Her retired teacher’s pension met her mortgage and basic food costs, but little beyond that. For five years I’d covered her $180 monthly auto insurance. When she complained that grocery shopping had become difficult, I arranged home deliveries and funded their $400 monthly bill.
My brother Jordan’s gas and electricity had been charged to my payment method for three years, another $220 each month. Vacations, festive meals, children’s birthday presents—all generally came from me.
I avoided calculating the full expense. A total would force me to acknowledge that the relationship had become an ongoing transaction, when for thirty-five years I’d preferred to call it affection.
The truth was harsher. I was supporting a permanent family expense account I’d never dared close.
Jordan, thirty-eight, worked as a construction foreman. He had a wife, Lindsay, two children, and an unquestioned position as Martha’s favorite. He’d remained nearby; I’d moved only twelve miles away for a career Mom dismissed as “your office thing.” At celebrations he got first consideration, and every mistake was excused with astonishing speed.
He’d declared bankruptcy at twenty-nine, lost a vehicle to repossession at thirty-one, and repeatedly borrowed from Martha. She covered his loans by asking me for more. This arrangement had been in place since I was twenty-six. I supplied the power, Jordan enjoyed the ride, and Mom directed traffic without worrying about the fuel.
Audrey was eighteen, three weeks past high-school graduation and accepted at State University for fall. For four years she’d saved whatever she earned. At fourteen she began weekend babysitting; at sixteen she took summer shifts on the reception desk at a veterinary practice, then added holiday retail hours at a downtown clothing shop.
Each paycheck went into an account she’d opened with Martha at fourteen. Because Audrey was underage and I was working during their bank visit, Mom became a joint signer. Nobody thought to remove that authority afterward.
Two weeks before this conversation, Audrey had checked her balance: $5,400. She’d told me over dinner, quietly pleased in the way people are when a long-held goal finally looks achievable.
Beside her phone charger and a well-worn college orientation handbook she’d read three times stood a glass jar. It held a single dollar, folded in half twice. Purple writing, carefully formed by a fourth grader, identified it:
“College money.”
She’d made it at ten after setting up a lemonade stall on our sidewalk for two July Saturdays. The enterprise brought in eleven dollars. She saved one and bought poster board for a school assignment with the remaining ten, saying the project mattered more.
Even at that age she understood priorities and the difference between saving and spending. That was the child my mother had chosen to take from.
The jar wasn’t the actual account, of course. It represented the beginning of Audrey’s plan. It had sat on her nightstand for eight years and survived two apartment moves. One Sunday, I repaired its cracked lid with epoxy while she watched and warned, “Careful, Mom. That jar is older than me.”
Inside remained that first bill and the belief attached to it: keep working, save patiently, and eventually another opportunity opens. Audrey never imagined someone trusted with guarding that opportunity would take the money behind her back.
“What do you mean, empty?”
My coffee hadn’t cooled, yet my stomach already felt frozen. Audrey showed me her banking app. The displayed balance was zero.
She’d attempted an $800 tuition deposit that morning to secure her place for fall, only to have the payment rejected. A bank representative told her the account was closed out after a March 14 withdrawal. Someone had taken all $5,400 at once.
“I didn’t withdraw anything,” Audrey said.
She sounded bewildered rather than angry, the way you do when something familiar suddenly proves unreliable in a way you never knew was possible.
I set down my mug and retrieved my laptop. The account portal took eight seconds to load. Transactions appeared as an ordinary sequence until the one that didn’t belong: March 14, $5,400 withdrawn by authorized signer Martha Novak.
Audrey sat next to me and permitted the banker to speak with me on speakerphone. They confirmed the transaction had been made by a person legally listed on the account. The bank considered the authorization valid because Martha’s joint-signing status remained in force from Audrey’s childhood. It could not simply reverse the payment. Recovery of the money would have to be pursued through civil proceedings.
Valid access didn’t mean rightful ownership. It just explained why the bank hadn’t stopped her.
My investigative instincts took over. When a payroll discrepancy or benefit claim raises suspicion, I don’t study only the questionable entry. I examine the surrounding history, looking for a longer pattern. A discovered problem is rarely the first one.
Seven earlier withdrawals appeared. There was $300 on January 8; $450 on September 22 the previous year; $200 on June 4; $150 on March 3; $250 on November 15; and two more, $175 and $275, during the preceding spring.
Every withdrawal was small enough to escape a routine alert and placed between Audrey’s deposits, leaving the balance looking normal when she made casual checks. Martha had been taking from the account since Audrey was sixteen.
Adding the entries produced $7,200 over twenty-four months, taken from a teenager who’d earned it through modest wages, weekend jobs, and veterinary-clinic shifts that left her clothes smelling of dog shampoo.
Mom had drawn money out gradually, like pruning away branches while leaving enough greenery to conceal the damage. March 14’s final $5,400 withdrawal came one day before I confirmed the $27,000 vacation reservation.
She’d already seen the trip details in our family group chat. She knew when I’d be committed financially, and she apparently counted on Audrey discovering the loss only afterward. It looked planned rather than impulsive.
I shut the computer. Audrey stood in the doorway, phone in hand and orientation guide tucked under her arm. After four years of work, the eighteen-year-old had found that a trusted relative could erase her savings with one bank visit.
“Mom, did someone hack the account?”
“No, sweetheart. I am going to find out what happened. Give me 24 hours.”
If you’ve lived with relatives who expect one person to carry every burden while others take whatever they want, follow Karma Unfolded. My mother’s explanation for what she’d done would soon make me cancel a $27,000 holiday without a second thought.
That evening, I didn’t confront Martha. I examined the entries the way I would examine a payroll irregularity: quietly, carefully, and with more interest in evidence than excuses.
On Tuesday morning, I passed Jordan’s home on my commute. He remained the favorite son, the thirty-eight-year-old construction foreman whose difficulties were always regarded as more urgent than mine.
Martha had already told me over the phone Monday evening that she had withdrawn Audrey’s $5,400 for the down payment on Jordan’s kitchen renovation. The contractor supposedly needed money immediately, the kitchen was deteriorating, and Audrey could simply postpone college for a semester.
“She can earn it back,” Martha had said.
There had been no apology and no request, only a dismissal from someone who appeared to have forgotten how much labor earning $5,400 required.
Jordan’s place occupied a corner in a neighborhood built during the 1990s. Beige siding surrounded the house. The grass was mowed, although its borders needed trimming, and the kitchen window overlooked the side yard.
I drove slowly past. There was no construction truck, dumpster, scaffold, lumber pile, protective sheeting, or dust along the window frames. Through the glass I could see the old 1994 oak cabinets, laminate counter, and narrow crack in the tile over the sink. Nothing had changed since Jordan bought the home six years before.
Public county permit searches didn’t require professional credentials. I entered the address and found nothing: no approved, pending, or requested permit.
There was no active remodeling job. Either Mom had invented its purpose or she hadn’t bothered checking before helping herself to the savings. Neither possibility excused what she’d done.
Later, after reviewing a workplace termination case involving three months of falsified time sheets, I continued tracing the money. When the explanation for a payment leads nowhere, an investigator looks for the actual destination.
Karen’s cousin was employed at the county courthouse and directed me to the searchable civil filings. A private loan wouldn’t ordinarily be visible, but a credit union had submitted a public default notice after two missed payments.
The documents identified Jordan Novak as borrower and Martha Novak as co-signer. The original loan was $14,000. To bring it current before the April quarterly review, the borrower needed exactly $5,400.
Not a rounded estimate. Precisely the sum withdrawn from Audrey’s account on March 14.
Mom had selected the amount to satisfy a particular obligation by a particular deadline. Jordan had borrowed $14,000 without Lindsay knowing; Martha had co-signed without telling me. When payments fell behind, Mom used a young woman’s college savings to rescue a grown man who couldn’t explain his debt to his own wife.
All the while she called it a nonexistent kitchen renovation. She dismissed Audrey’s four years of earnings—summer after summer, weekends and holidays, sometimes at nine dollars an hour—as money the girl could easily replace. To Martha, “she can earn it back” excused everything.
That night I phoned Karen Webb, my closest friend since college. We’d shared adjacent dorm rooms during sophomore year, separated by a wall so thin we could hear each other’s morning alarms.
Karen was now a marketing director with two cats and no children. People called her blunt. I called her honest. When something in my life fell apart, she was the one person who wouldn’t insist on repairing it before I decided what I needed.
Six months earlier, Audrey’s State University acceptance had prompted Karen to drive forty minutes to our house on a Wednesday night with a homemade cake. Its blue frosting said “Statebound,” in crooked letters. Karen knew marketing better than baking, but the message mattered more to her than straight lines.
When Audrey opened the acceptance envelope, shrieked, and jumped, Karen caught her in her arms. It seemed she’d been anticipating that celebration since the evenings Audrey studied for her SATs at my kitchen table. I watched from the doorway as Karen looked over Audrey’s shoulder and silently mouthed:
“You did this.”
That recognition meant more to me than the acceptance itself. Someone outside our family appreciated my daughter’s achievement and rejoiced more wholeheartedly than the people related to us.
I gave Karen the details: eight withdrawals, the $7,200 total, the false kitchen story, the absence of permits, the credit-union default, and Mom’s co-signature. Karen didn’t interrupt. When she’s furious, she becomes an unusually patient listener.
“What are you going to do?” she said.
“Cancel the resort. All $27,000, every dollar.”
“Good.”
Initially I considered canceling without warning, allowing everyone to reach the resort and discover it themselves. Then I noticed the holiday brochure lying on the counter.
Audrey had circled snorkeling, a sunset kayak excursion, and a spa experience. Beside the latter, she’d written “Mom and me” with a smiling face in gel ink.
The brochure had been there three months. Every few days she looked through it again, adding activities, assigning excursions to dates, and planning what she’d order at the resort restaurant on our first night. She’d been behaving like an ordinary excited teenager with something wonderful ahead of her.
Now those circled plans were being sacrificed because Martha considered Jordan’s concealed debt more important than his niece’s future. I wouldn’t let the family pretend the canceled vacation was an inexplicable act of spite. They would hear precisely what had caused it.
Thursday at 6:15 p.m., I called the resort. Only my name appeared on the booking, with my email and credit card. Its terms allowed a complete refund if canceled at least seventy-two hours before check-in, scheduled for Sunday at two.
I called with seventy-two hours and fifteen minutes remaining. Four minutes later, the representative had released all four ocean-view, all-inclusive rooms for the seven-night stay.
The cancellation confirmation came at 6:18 p.m. My entire $27,000 would return to the card within ten business days.
Neither Martha nor Jordan knew. As with the other family expenses, nobody had considered the practical importance of who actually booked and financed the arrangement.
I spent the remaining evening withdrawing support I’d been providing without conditions. Martha’s car insurance, $180 monthly for five years—a total of $10,800—would end Monday. That took seven minutes and a confirmation code.
I removed my card from Jordan’s utility account, ending three years of $220 monthly payments. With automatic payments stopped, a past-due notice would reach him within two weeks.
I also terminated Martha’s grocery delivery subscription, the $400 monthly charge I’d financed since her retirement. She would need to shop for herself or arrange help from someone else.
In a single evening I ended $800 of monthly support, canceled a $27,000 vacation, and began preparing to recover $7,200 from my mother.
On Friday, Audrey and I visited another bank and opened an account exclusively in her name. No shared signer, no grandmother authorized to withdraw, no outside access.
Our banker noticed the opening deposit was only one dollar but politely didn’t ask about it. Audrey laid the familiar bill on the counter: her original lemonade-stand dollar, removed from the jar after eight years. She was beginning again on the same foundation she’d built at ten.
After canceling the resort, I almost called Martha. Her number filled my screen while anger gathered behind my teeth. Looking through Audrey’s bedroom door, though, I saw the glass jar with its purple label. Its space was empty now that the dollar was in the new account, but the jar remained standing.
I set down my phone.
On Wednesday, I had asked Karen to join me for Sunday dinner at Mom’s house. Karen agreed without demanding an explanation of the plan. Some friends simply know when you need another steady person in the room.
Saturday morning, 9:14 a.m. My phone rang with a call from Martha.
“Brooke, I am standing at the front desk of the Ocean View Palms Resort, and they are telling me there is no reservation under Novak.”
Her voice was taut, rising almost to a shriek.
“There is no reservation under any name they can find. I have my suitcase. Jordan and Lindsay are in the parking lot unloading the car. The children are asking about the pool. What is happening?”
I could hear gentle music behind her and families passing through the foyer. Wheels rolled over tile, employees greeted new arrivals, and a vacation destination continued operating normally for everyone except my relatives.
“There is no reservation, Mom.”
“What do you mean there is no reservation? You booked four rooms. You sent the confirmation. We drove 3 hours. Jordan took time off work. Lindsay packed for the children. Brooke, what did you do?”
“I canceled it Thursday evening.”
Four seconds passed without a reply. Somewhere nearby, the receptionist cheerfully asked another guest about the trip there.
“You canceled the whole thing? A $27,000 vacation without telling anyone?”
“You withdrew $5,400 from Audrey’s college account without telling her. And before that, you took another $1,800 in withdrawals you thought nobody would notice. Tomorrow at dinner, we are going to talk about all of it. Drive home safely.”
“Mom. Brooke. Brooke, wait. Jordan and Lindsay are standing in the parking lot with their suitcases. The children are crying. They can see the pool from the parking lot. Do you understand what you are doing to this family?”
“Do you understand what you did to Audrey?”
She said nothing. The reception agent was still greeting other visitors; I heard the happy conversations of arriving families and the small electronic tone of a freshly programmed room card. Their vacations were proceeding as planned.
“Drive home,” I said again. “Sunday dinner is at 5.”
I ended the call and left the phone facedown. Audrey’s brochure, full of gel-pen circles, was in a kitchen drawer. I folded it once more and placed it beneath the account statements. The evidence now seemed heavier than all the plans on those colorful pages.
Then I made another cup of coffee and settled at the table where Audrey had spent countless evenings doing homework. The house felt unusually quiet. I’d finally ended a pattern that should have stopped long before, but relief hadn’t yet overcome the hurt.
If the vacation cancellation seems like the toughest part of that weekend, stay with Karma Unfolded. What happened at Sunday dinner was the moment our family finally had to confront the truth.
Sunday, five o’clock. Martha’s dining room. Seven places had been prepared around the table.
Mom was still in the kitchen and hadn’t raised the resort incident since our phone call. Jordan and Lindsay were already seated. He leaned back with his arms folded, as though he’d been told I’d created unnecessary conflict and had come ready to defend his position. Lindsay sat quietly, repeatedly rearranging her napkin.
Karen occupied the seat beside me, phone resting in her lap. She wasn’t making a recording. She was simply ready to support me, the way a witness can be ready without announcing herself.
Mom carried dishes to the table while deliberately avoiding my eyes. The stiffness of her movements told me she’d chosen to behave as though nothing had happened and wait for me to retreat, as I had always done.
For thirty-five years she’d seen me concede. Jordan received more attention at holidays; she overlooked Audrey’s birthdays while remembering his children’s; my money was expected at gatherings even when my presence seemed optional. Nothing had ever taught Mom that I would enforce a limit.
Roast chicken and fresh bread scented the dining room. Martha had brought out her best china, performing ordinary family hospitality as if perfect table settings could make the discussion disappear. Jordan began eating. Lindsay sliced her meal into nervous little portions. Karen rested both hands on the table and remained still.
Once everybody had food, and Mom was settled with Jordan’s fork already raised, I began.
“Mom, when did you last check Audrey’s savings account?”
Her fork halted midway to her lips.
“What?”
“Audrey’s savings account. The one you co-signed when she was 14. When did you last look at the balance?”
“I do not check her account, Brooke. That is her private business.”
“That is interesting because the bank’s records show eight transactions on that account authorized by your name over the last two years. If you were not checking the balance, you were certainly checking the withdrawal limits.”
Martha lowered her fork. Jordan stopped chewing and looked between us.
“The most recent withdrawal was March 14th,” I said. “$5,400. The entire remaining balance authorized by Martha Novak.”
“We already talked about this on the phone,” Martha said.
Her careful, deliberate manner showed she was choosing each word.
“Jordan needed it for the kitchen. I told you she can earn it back.”
“You did tell me that, and I believed you for about 12 hours. Then I drove past Jordan’s house on Tuesday morning.”
Jordan shifted his attention toward me.
“Same cabinets, same countertop, same cracked tile above the sink. No scaffolding, no dumpster, no contractor truck, no stacked materials. I checked the county permit database from the car. No building permits filed for your address in the last 12 months, Jordan. No plumbing, no electrical, nothing pending.”
“I haven’t started yet,” Jordan said. “The contractor is coming next month.”
“What is his name?”
“A guy Darren recommended. I do not remember his last name.”
“What company?”
“I do not have to give you his company name. Brooke, this is not a job interview.”
“You are right. It is not. But the county requires a filed permit before any structural or plumbing work begins in a residential kitchen, and nothing has been filed. If you have a contractor coming next month, he has not pulled permits, which means either he does not exist or he is unlicensed. And if he is unlicensed, the county can stop the work and fine you.”
Jordan looked toward Mom for help, but she was studying the tablecloth.
“But the permits are not the reason I brought this up tonight,” I said.
I removed the first statement from my bag and laid it between the bread rolls and salt shaker.
“March 14th, $5,400.”
I added another.
“January 8th, $300.”
And another.
“September 22nd of last year, $450.”
Then the next.
“June 4th, $200.”
The pages accumulated with the quiet weight of documentary evidence. Seven statements lay on the table, each representing one of the withdrawals recorded under the same signer’s name, all made across two years. Together with the final amount, the total was $7,200.
“Every one of them authorized by you, Mom. Every one of them taken from a savings account that belonged to a teenager who earned every dollar working summers and weekends and holidays.”
Martha pressed her hands against the table as her face tightened.
“You have no right to go through her bank records,” Martha said.
“She is my daughter. She is 18. She asked me to. And you were co-signer on a minor’s account, which means every withdrawal you made is documented, timestamped, and legally traceable.”
No one spoke. Lindsay forgot about her napkin. Jordan studied the documents as if refusing to understand what he was seeing might somehow make the transactions go away.
“And the $5,400 did not go to a kitchen remodel,” I said. “I checked. There is no remodel. There is no contractor. What there is, Mom, is a co-signer document on a personal loan that Jordan took out 11 months ago. A loan he never told Lindsay about. You co-signed it. And the $5,400 went to pay it down before the next review.”
Lindsay turned to her husband. Her napkin slipped onto the floor unnoticed.
“What loan?”
Jordan clenched his jaw, a muscle near his ear twitching.
“It is not what she is making it sound like.”
“What loan, Jordan?”
Her voice had lost its habitual softness. The question was suddenly sharp.
“A personal loan. 11 months ago. $14,000. Mom co-signed $14,000.”
Lindsay repeated what she had heard, trying to believe it.
“You took out a $14,000 loan. And you did not tell me. We share a mortgage. We share a checking account. We have two children in this house. And you walked into a credit union and took out $14,000 with your mother’s signature instead of mine.”
“It was for the truck repairs and some other things that came up. I was going to tell you when it was paid off.”
“When it was paid off with what money, Jordan? Because the money that paid it down came from Audrey’s college account.”
“Your mother stole from your 18-year-old niece so you could hide a debt from your wife. Is that what just happened at this table?”
“That is not how I would describe it,” Jordan said.
“Then how would you describe it? Because I have been sitting here for 20 minutes watching your sister lay out bank statements and permits and loan documents, and you have not denied a single one. You have not said ‘that is wrong’ or ‘that is not mine.’”
“You have said ‘I have not started yet’ and ‘it is not what she is making it sound like.’ Those are not denials, Jordan. Those are stalls.”
Jordan sought out Mom’s expression again, but she didn’t lift her eyes. Statements occupied the space between dinner plates and serving bowls, records neither of them could meaningfully refute.
Karen hadn’t spoken. She didn’t need to. The numbers and pauses told their own story. In little more than a minute, Lindsay’s confusion had turned into disgust, a transformation more powerful than any speech Karen might have offered.
Martha stood, placing one hand behind her chair and the other on her chest.
“My heart is racing. I think I am having palpitations. Brooke, this stress is going to put me in the hospital. I need to sit in the other room.”
I’d seen versions of that performance for years. Whenever dinner conversation neared a subject Mom wanted to avoid, a physical symptom materialized: headaches over finances, stomach troubles during comparisons involving Audrey’s grades and Jordan’s children, a rapid heartbeat whenever someone asked an unwelcome question.
It was the escape door she reached for whenever accountability approached.
“If you are having a medical event, I will call 911 right now,” I said. “If you are performing, sit down and listen because I am not finished.”
She watched me for three seconds and sat. Her hand remained pressed to her chest another ten seconds before dropping out of view into her lap.
“You took $7,200 from your granddaughter’s college savings account over 2 years,” I said. “You told me the last $5,400 was for a kitchen remodel that does not exist. The money went to a personal loan Jordan took without telling his wife, a loan you co-signed without telling me. You timed the final withdrawal one day before I confirmed a $27,000 resort booking because you knew I would already be committed before Audrey discovered the loss.”
I faced my brother.
“And you let your mother steal from an 18-year-old girl who worked 4 years at minimum wage to cover a debt you were too ashamed to tell your own wife about.”
Then I turned back to Martha.
“My attorney has the bank records, the county’s no-permit result, and the default notice with your co-signature. The demand letter for $7,200 goes out tomorrow. The amount is under the county’s small claims limit, which is why we are keeping this simple. If it is not repaid within 30 days, I file.”
Her mouth narrowed and her eyes filled. Finally she said what she’d apparently been holding back since the resort call.
“That girl has been spoiled since the day you put a jar on her shelf and told her the world owed her a degree. Jordan has a family to hold together. His house is falling apart. Your daughter can wait one semester and get a job like everyone else instead of floating through life on your credit card. She is not special just because you decided she was, Brooke. And neither is that jar.”
That attack reached in several directions at once. Martha belittled Audrey’s work, my parenting, the meaning of the little jar, and our decision to invest in college. She elevated Jordan’s troubles above Audrey’s education while implying that my daughter lived on borrowed privilege.
I stayed quiet enough to be heard clearly.
“Audrey is not special because I decided she was. Audrey is special because she worked two summers, three weekends a month, and every holiday break to put $5,400 into a savings account that you drained in one withdrawal while telling me she could earn it back. She already earned it. You are the one who took it.”
Martha opened her mouth without producing a reply. Her right hand clenched the table’s edge, her shoulders curling inward as her breathing shortened.
“The resort is cancelled. The bills are ending. The demand letter goes out tomorrow.”
I reached into my bag and brought out Audrey’s glass jar. Its purple label faced Martha, showing the words formed by a ten-year-old who had believed that patient work would lead to something worth having.
“College money” in purple marker.
“That jar is still on her nightstand. It still says ‘college money’ in purple marker. It is the only thing you did not take.”
Martha released the table and held her chair. Her shoulders sagged abruptly; her lips parted, but nothing followed. Her breathing remained shallow. For the first time since I’d started speaking, she seemed to comprehend that I wasn’t going to apologize just to restore the family’s comfort.
I set the jar between the financial records and salt shaker and got to my feet. Karen rose alongside me. We walked toward the dining room exit, leaving Lindsay standing, Jordan immobile in his chair, and Martha staring at the jar as though it represented something she no longer controlled.
The only sounds were a wall clock and Jordan’s little daughter asking her brother in the adjoining room whether she could have his juice box.
I nearly ended matters there: the refund, the formal demand, and our departure, with no more explanations. But I remembered the lemonade stall.
Audrey had sat in a folding chair beneath the July sunshine on two Saturdays when she was ten, spending four hours there each day. Her sign was handwritten, the lemonade illustrated from an internet recipe. Eleven dollars was the total reward for her effort. She saved one, marked the jar, placed it by her bed, and announced:
“That’s the start.”
She hadn’t been acting on my orders. She wanted a future larger than her present and believed effort could build it. For eight years her grandmother’s behavior had quietly undermined that trust. Audrey deserved a complete accounting, not simply the sight of me leaving the room.
From the front entrance, I spoke loudly enough to reach everyone at the table.
“I am canceling your car insurance Monday,” I said from the front door, loud enough for the dining room to hear. “5 years of premiums, $10,800 total. The grocery deliveries are cancelled. Jordan’s utility autopay is removed. The resort refund is mine. My attorney sends the demand letter for $7,200 tomorrow.”
“Do not call me about any of it. Do not ask Audrey to forgive you before she is ready. And do not come to my house until you are ready to repay what you took from an 18-year-old girl who earned it at $9 an hour.”
I shut the door behind us. Karen and I went to the car in silence. A minute passed before she spoke.
“You should have done that years ago.”
“I know.”
By Monday morning, the financial consequences started reaching Martha, each one arriving with the ordinary insistence of a bill that finally belonged to its rightful payer.
Her insurance app displayed a warning in red.
“Policy not active.”
When she telephoned the insurer, its representative explained that Brooke Novak, the policyholder, had ended coverage effective that Monday. Martha’s Honda remained parked in the drive because driving without insurance was unlawful.
That afternoon she contacted three companies for replacement coverage. The least expensive option she could find on her teacher’s pension was $240 a month—sixty dollars higher than the bundled premium I’d been paying. She enrolled on Thursday, making her responsible for her first auto insurance payment in five years.
The next Monday, Jordan’s electricity provider issued an overdue notice. My card was no longer attached to his account, and $220 had to be paid within fourteen days. Lindsay, meanwhile, was staying with her sister and had taken the children along. She was deciding whether she could trust a husband who’d hidden a fourteen-thousand-dollar personal loan.
Before agreeing to return home, she required Jordan to sign a written arrangement promising repayment of his share of the $5,400, with her sister witnessing it. He signed without objecting at their kitchen table. It was the first time in eleven months he’d acknowledged a financial obligation openly in a document bearing his own name.
Tuesday’s email brought Martha confirmation that the grocery delivery service was canceled. For the first time in two years, she drove to the supermarket herself. She spent $127, returned home, and carried the bags inside without anyone else paying or arranging the errand.
On Wednesday, the certified demand reached her. The letter specified $7,200 and listed each withdrawal date and amount. It gave her thirty days to repay before I sought relief in the county’s small-claims court.
Mom read the letter twice at her kitchen table. Afterward she folded it beside her plate and the telephone that had remained quiet since the Sunday confrontation.
Two weeks later, on Tuesday evening, that phone finally rang. The caller was Donna, Martha’s closest friend from thirty years of teaching together. Donna’s voice held none of its usual warmth.
“Martha, is it true you took Audrey’s college savings? Somebody at church told me, and I told them they were wrong. Then Karen’s mother showed me the whole story.”
“It was a family matter, Donna. It is being handled.”
“Handled how? My daughter works in the registrar’s office at State. She told me Audrey’s enrollment was on hold for 2 weeks because of a missing deposit. That girl almost lost her spot because you cleaned out her account. Is that true?”
Martha couldn’t answer. Donna continued without softening.
“I have five grandchildren, Martha. If I took $1 from any of their college accounts, I would not be able to look at myself in the mirror for the rest of my life. I think you need to fix this. Fix it before Easter. Fix it before Audrey’s first semester starts, and fix it before you call me again because I do not want to hear your voice until you have made this right.”
The call ended. Martha kept the receiver to her ear for several seconds, hearing only the dial tone where a decades-long friendship had once been. The regular Thursday lunches with Donna were finished, and the phone stayed quiet for the rest of that week.
Three weeks after our dinner, Jordan’s six-year-old daughter sat over a bowl of cereal on a Saturday morning. Lindsay had returned to the house, although the tension between her and Jordan remained. The child set down her spoon and asked with the unguarded directness of someone too young to understand adult secrets:
“Mommy, why doesn’t Aunt Brooke come to dinner anymore? And where did Audrey go?”
Lindsay paused while loading the dishwasher and looked toward her husband. Jordan, seated opposite their daughter, had been scrolling through his phone. He put it down, fixed his eyes on his breakfast, and avoided looking at the little girl.
There was no answer a six-year-old could easily understand. Her aunt wasn’t coming because Grandma had taken Audrey’s college fund, and her father had hidden a debt. Nobody had apologized before the silence became impossible to ignore.
Martha allowed the demand letter’s thirty-day deadline to expire without repayment or a response. The next Tuesday, my attorney filed the case in small claims. The hearing was scheduled for June, two months before Audrey’s anticipated move into university housing. Martha would receive formal notice, and Jordan was identified as the recipient who benefited from the funds.
Then came September, and move-in day at State University. Audrey hauled three boxes up two flights of stairs. I followed with two more. Karen carried a lamp and a packet of hangers purchased from Target that morning. In her view, every dormitory required at least twelve hangers, a fact Audrey would supposedly appreciate by October.
The room was basic: off-white painted cinder-block walls, a window overlooking a parking area and narrow lawn where two students tossed a Frisbee, a desk, one chair, and a twin mattress that squeaked under Audrey’s weight when she tested it.
She unpacked her last box. Inside, protected by a dish towel, was the glass jar. She lifted it gently, as though its history made it heavier than the ordinary object in her hands. She placed it on the desk’s corner with the writing turned outward.
“College money.”
Eight years of sunlight through a bedroom window had faded the purple writing at its edges, but every letter could still be read. There was no dollar inside anymore. That first bill now belonged to her new bank account, where she alone controlled the balance and no other signer could withdraw it.
The jar was empty, but its purpose hadn’t ended. It still marked a beginning, one Audrey was making for herself all over again.
She placed a framed photograph beside it: Brooke, Audrey, and Karen on the night of the acceptance celebration. The blue-frosted “Statebound” cake could be seen behind us. Karen’s arm surrounded Audrey’s shoulders, while only half my face showed in the doorway. I’d been watching rather than posing, as I often had throughout my life.
Watching, providing, keeping the lights on, standing outside the center of every picture so everyone else could take their places. For years I had made myself the person who ensured other people’s lives continued smoothly.
Karen’s mother later told me that Martha’s dining table had one fewer chair occupied. The resort brochure lay untouched in a drawer. A magnet held the certified demand letter against the refrigerator, in the spot where Audrey’s school pictures used to hang before Martha removed them.
Martha now paid for her own car insurance at a higher rate. Jordan’s electric account had been brought current because Lindsay required him to arrange his own automatic payments before she returned. His personal loan, however, remained unpaid.
None of those burdens belonged to Audrey anymore. Her small college room was bright, and most importantly, it was hers.
The glass jar occupied a spot on the desk between her macroeconomics textbook and a coffee mug Karen had given her, bearing the words “Earned it.” Afternoon light shone through its empty sides and illuminated the purple inscription.
What it held now wasn’t money. It held a memory of a ten-year-old girl who believed she could build a future by saving what she earned. The belief had been tested harshly, but its owner was still there, continuing what she had started.
I stood against the doorframe with my arms folded, watching Audrey arrange her belongings and begin a life nobody could simply empty out from under her. The faded letters caught the light, and the little girl who had written them had finally reached the place she had worked toward.
If you’ve recognized the kind of relatives who say “she can earn it back” while never having done that work themselves, or you know how difficult it is to enforce a boundary you should have set years ago, subscribe to Karma Unfolded.
I’ll see you in the next story.